Saltar al contenido principal
Cooper Industries Proposal to
Acquire Nicholson File Company
MAY 3, 1971
Previous Acquisitions
 1967
Lufkin Rule Company
 1969
Crescent Niagara Corporation
 1970
Weller Electric Corporation
Criteria for Acquisition
1. Industry must be one where Cooper Industries
can be a major leader
2. Industry must be stable, with a broad appetite
for “small ticket” items
3. Only acquire leading companies in their
respective markets
Nicholson File Company Strengths
 One of the largest domestic manufacturers of hand tools
 50% market share of $50 million market for files and rasps
 9% market share of $200 million market for hand saws and saw
blades
 Only Sears, Roebuck, and Company and Disston hold larger shares
 48 salespeople and 28 file and saw engineers
 Marketed to 2,100 hardware wholesalers
 Products in 53,000 stores
 Sold in 137 countries
Why Merge?
 Opportunity to leverage complementary product
offerings between Cooper and Nicholson
 Increased long-term growth potential by increasing
exposure of respective product lines to new markets and
customers
 Annual synergies from the reduction of COGS and SG&A
Financial Implications of Merger
Cooper Industries & Nicholson File Company
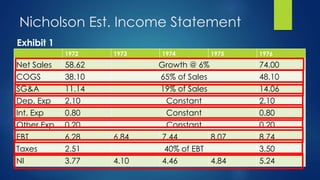
Nicholson Est. Income Statement
1972 1973 1974 1975 1976
Net Sales 58.62 Growth @ 6% 74.00
COGS 38.10 65% of Sales 48.10
SG&A 11.14 19% of Sales 14.06
Dep. Exp 2.10 Constant 2.10
Int. Exp 0.80 Constant 0.80
Other Exp. 0.20 Constant 0.20
EBT 6.28 6.84 7.44 8.07 8.74
Taxes 2.51 40% of EBT 3.50
NI 3.77 4.10 4.46 4.84 5.24
Exhibit 1
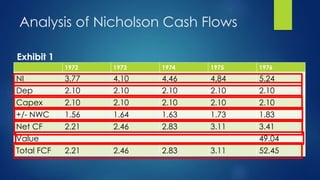
Analysis of Nicholson Cash Flows
1972 1973 1974 1975 1976
NI 3.77 4.10 4.46 4.84 5.24
Dep 2.10 2.10 2.10 2.10 2.10
Capex 2.10 2.10 2.10 2.10 2.10
+/- NWC 1.56 1.64 1.63 1.73 1.83
Net CF 2.21 2.46 2.83 3.11 3.41
Value 49.04
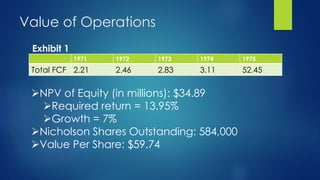
Total FCF 2.21 2.46 2.83 3.11 52.45
Exhibit 1
Value of Operations
1971 1972 1973 1974 1975
Total FCF 2.21 2.46 2.83 3.11 52.45
NPV of Equity (in millions): $34.89
Required return = 13.95%
Growth = 7%
Nicholson Shares Outstanding: 584,000
Value Per Share: $59.74
Exhibit 1
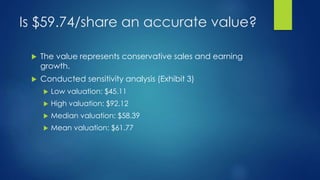
Is $59.74/share an accurate value?
 The value represents conservative sales and earning
growth.
 Conducted sensitivity analysis (Exhibit 3)
 Low valuation: $45.11
 High valuation: $92.12
 Median valuation: $58.39
 Mean valuation: $61.77
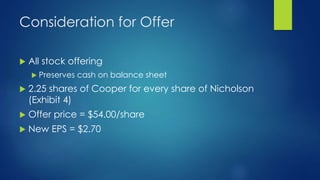
Consideration for Offer
 All stock offering
 Preserves cash on balance sheet
 2.25 shares of Cooper for every share of Nicholson
(Exhibit 4)
 Offer price = $54.00/share
 New EPS = $2.70
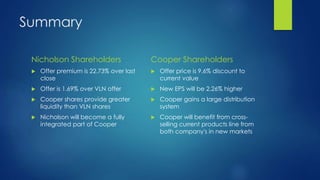
Summary
Nicholson Shareholders
 Offer premium is 22.73% over last
close
 Offer is 1.69% over VLN offer
 Cooper shares provide greater
liquidity than VLN shares
 Nicholson will become a fully
integrated part of Cooper
Cooper Shareholders
 Offer price is 9.6% discount to
current value
 New EPS will be 2.26% higher
 Cooper gains a large distribution
system
 Cooper will benefit from cross-
selling current products line from
both company's in new markets