Saltar al contenido principal
LVMH
MOËT HENNESY LOUIS VUITTON
FINANCIAL ANALYSIS
by
GROUP C – Master in Management 2015
Company Profile
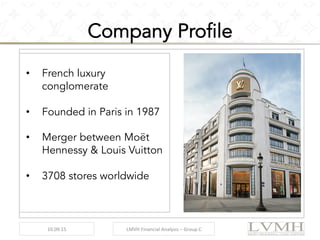
•  French luxury
conglomerate
•  Founded in Paris in 1987
•  Merger between Moët
Hennessy & Louis Vuitton
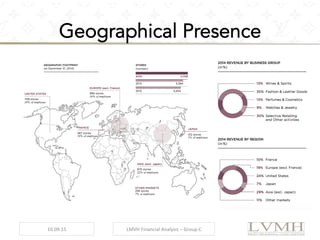
•  3708 stores worldwide
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
•  Highly dependent on consumer preferences & short-living fashion
trends
•  Difficulty to establish long-term brand loyalty
•  Relatively unaffected by macroeconomic trends
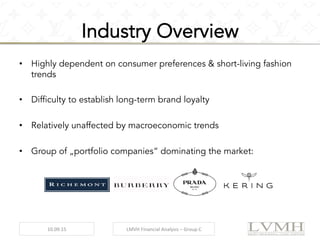
•  Group of „portfolio companies“ dominating the market:
	
  
Industry Overview
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Corporate Strategy
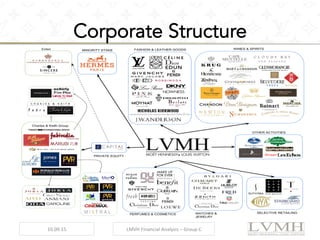
•  Conglomerate of luxury companies
•  Diverse brand portfolio through M&A activity
•  Mother company set values for different companies but
leave autonomy to fashion designers
•  Owning stores (prime CRE) & land (Champagne)
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
•  1984 acquired and became CEO
of Christian Dior
•  1987 helped mediate a conflict at
LVMH
•  1988 gained control at LVMH as a
large stakeholder preventing
dismantlement
•  90‘s - present: Made LVMH what it
is today through long list of
acquisitions
	
   10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Le Chef – Bernard Arnault
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Corporate Structure
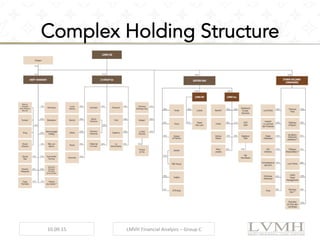
Complex Holding Structure
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Geographical Presence
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
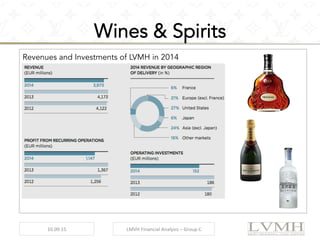
Wines & Spirits
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
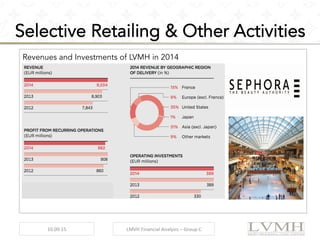
Revenues and Investments of LVMH in 2014
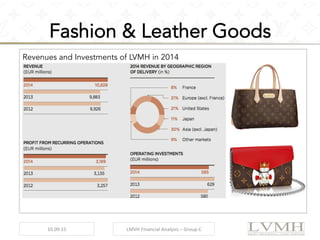
Fashion & Leather Goods
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Revenues and Investments of LVMH in 2014
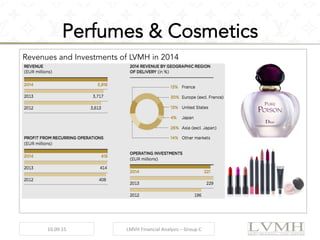
Perfumes & Cosmetics
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Revenues and Investments of LVMH in 2014
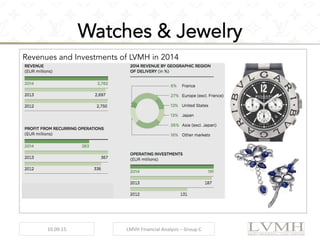
Watches & Jewelry
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Revenues and Investments of LVMH in 2014
Selective Retailing & Other Activities
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Revenues and Investments of LVMH in 2014
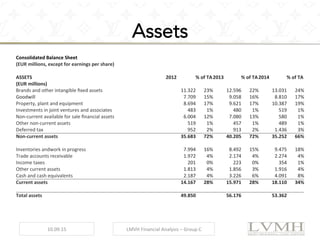
Assets
Consolidated	
  Balance	
  Sheet	


(EUR	
  millions,	
  except	
  for	
  earnings	
  per	
  share)	


ASSETS	
   2012	
  	
   %	
  of	
  TA	
  2013	
  	
   %	
  of	
  TA	
  2014	
  	
   %	
  of	
  TA	
  
(EUR	
  millions)	


Brands	
  and	
  other	
  intangible	
  fixed	
  assets	
   11.322	
  	
   23%	
   12.596	
  	
   22%	
   13.031	
  	
   24%	
  
Goodwill	
   7.709	
  	
   15%	
   9.058	
  	
   16%	
   8.810	
  	
   17%	
  
Property,	
  plant	
  and	
  equipment	
   8.694	
  	
   17%	
   9.621	
  	
   17%	
   10.387	
  	
   19%	
  
Investments	
  in	
  joint	
  ventures	
  and	
  associates	
   483	
  	
   1%	
   480	
  	
   1%	
   519	
  	
   1%	
  
Non-­‐current	
  available	
  for	
  sale	
  financial	
  assets	
   6.004	
  	
   12%	
   7.080	
  	
   13%	
   580	
  	
   1%	
  
Other	
  non-­‐current	
  assets	
   519	
  	
   1%	
   457	
  	
   1%	
   489	
  	
   1%	
  
Deferred	
  tax	
   952	
  	
   2%	
   913	
  	
   2%	
   1.436	
  	
   3%	
  
Non-­‐current	
  assets	
   35.683	
  	
   72%	
   40.205	
  	
   72%	
   35.252	
  	
   66%	


Inventories	
  andwork	
  in	
  progress	
   7.994	
  	
   16%	
   8.492	
  	
   15%	
   9.475	
  	
   18%	
  
Trade	
  accounts	
  receivable	
   1.972	
  	
   4%	
   2.174	
  	
   4%	
   2.274	
  	
   4%	
  
Income	
  taxes	
   201	
  	
   0%	
   223	
  	
   0%	
   354	
  	
   1%	
  
Other	
  current	
  assets	
   1.813	
  	
   4%	
   1.856	
  	
   3%	
   1.916	
  	
   4%	
  
Cash	
  and	
  cash	
  equivalents	
   2.187	
  	
   4%	
   3.226	
  	
   6%	
   4.091	
  	
   8%	
  
Current	
  assets	
   14.167	
  	
   28%	
   15.971	
  	
   28%	
   18.110	
  	
   34%	


Total	
  assets	
   49.850	


   56.176	


   53.362	


10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
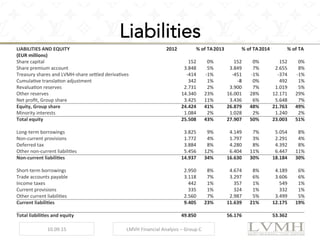
Liabilities
LIABILITIES	
  AND	
  EQUITY	
   2012	
  	
   %	
  of	
  TA	
  2013	
  	
   %	
  of	
  TA	
  2014	
  	
   %	
  of	
  TA	
  
(EUR	
  millions)	


Share	
  capital	
   	
  152	


   0%	
   	
  152	


   0%	
   	
  152	


   0%	
  
Share	
  premium	
  account	
   	
  3.848	


   5%	
   	
  3.849	


   7%	
   	
  2.655	


   8%	
  
Treasury	
  shares	
  and	
  LVMH-­‐share	
  se[led	
  derivaves	
   -­‐414	


   -­‐1%	
   -­‐451	


   -­‐1%	
   -­‐374	


   -­‐1%	
  
Cumulave	
  translaon	
  adjustment	
   	
  342	


   1%	
   -­‐8	


   0%	
   	
  492	


   1%	
  
Revaluaon	
  reserves	
   	
  2.731	


   2%	
   	
  3.900	


   7%	
   	
  1.019	


   5%	
  
Other	
  reserves	
   	
  14.340	


   23%	
   	
  16.001	


   28%	
   	
  12.171	


   29%	
  
Net	
  profit,	
  Group	
  share	
   	
  3.425	


   11%	
   	
  3.436	


   6%	
   	
  5.648	


   7%	
  
Equity,	
  Group	
  share	
   	
  24.424	


   41%	
   	
  26.879	


   48%	
   	
  21.763	


   49%	
  
Minority	
  interests	
   	
  1.084	


   2%	
   	
  1.028	


   2%	
   	
  1.240	


   2%	
  
Total	
  equity	
   	
  25.508	


   43%	
   	
  27.907	


   50%	
   	
  23.003	


   51%	


Long-­‐term	
  borrowings	
   	
  3.825	


   9%	
   	
  4.149	


   7%	
   	
  5.054	


   8%	
  
Non-­‐current	
  provisions	
   	
  1.772	


   4%	
   	
  1.797	


   3%	
   	
  2.291	


   4%	
  
Deferred	
  tax	
   	
  3.884	


   8%	
   	
  4.280	


   8%	
   	
  4.392	


   8%	
  
Other	
  non-­‐current	
  liabilies	
   	
  5.456	


   12%	
   	
  6.404	


   11%	
   	
  6.447	


   11%	
  
Non-­‐current	
  liabiliVes	
   	
  14.937	


   34%	
   	
  16.630	


   30%	
   	
  18.184	


   30%	


Short-­‐term	
  borrowings	
   	
  2.950	


   8%	
   	
  4.674	


   8%	
   	
  4.189	


   6%	
  
Trade	
  accounts	
  payable	
   	
  3.118	


   7%	
   	
  3.297	


   6%	
   	
  3.606	


   6%	
  
Income	
  taxes	
   	
  442	


   1%	
   	
  357	


   1%	
   	
  549	


   1%	
  
Current	
  provisions	
   	
  335	


   1%	
   	
  324	


   1%	
   	
  332	


   1%	
  
Other	
  current	
  liabilies	
   	
  2.560	


   7%	
   	
  2.987	


   5%	
   	
  3.499	


   5%	
  
Current	
  liabiliVes	
   	
  9.405	


   23%	
   	
  11.639	


   21%	
   	
  12.175	


   19%	


Total	
  liabiliVes	
  and	
  equity	
   	
  49.850	


  56.176	


  53.362	


10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
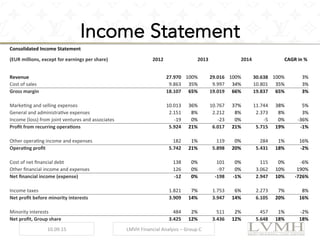
Income Statement
Consolidated	
  Income	
  Statement	


(EUR	
  millions,	
  except	
  for	
  earnings	
  per	
  share)	
   2012	


   2013	


   2014	


   CAGR	
  in	
  %	


Revenue	
   	
  27.970	


  100%	
   	
  29.016	


  100%	
   	
  30.638	


  100%	
   3%	
  
Cost	
  of	
  sales	
   	
  9.863	


   35%	
   	
  9.997	


   34%	
   	
  10.801	


   35%	
   3%	
  
Gross	
  margin	
   	
  18.107	


   65%	
   	
  19.019	


   66%	
   	
  19.837	


   65%	
   3%	


Markeng	
  and	
  selling	
  expenses	
   	
  10.013	


   36%	
   	
  10.767	


   37%	
   	
  11.744	


   38%	
   5%	
  
General	
  and	
  administrave	
  expenses	
   	
  2.151	


   8%	
   	
  2.212	


   8%	
   	
  2.373	


   8%	
   3%	
  
Income	
  (loss)	
  from	
  joint	
  ventures	
  and	
  associates	
   -­‐19	


   0%	
   -­‐23	


   0%	
   -­‐5	


   0%	
   -­‐36%	
  
Profit	
  from	
  recurring	
  operaVons	
   	
  5.924	


   21%	
   	
  6.017	


   21%	
   	
  5.715	


   19%	
   -­‐1%	


Other	
  operang	
  income	
  and	
  expenses	
   	
  182	


   1%	
   	
  119	


   0%	
   	
  284	


   1%	
   16%	
  
OperaVng	
  profit	
   	
  5.742	


   21%	
   	
  5.898	


   20%	
   	
  5.431	


   18%	
   -­‐2%	


Cost	
  of	
  net	
  financial	
  debt	
   	
  138	


   0%	
   	
  101	


   0%	
   	
  115	


   0%	
   -­‐6%	
  
Other	
  financial	
  income	
  and	
  expenses	
   	
  126	


   0%	
   -­‐97	


   0%	
   	
  3.062	


   10%	
   190%	
  
Net	
  financial	
  income	
  (expense)	
   -­‐12	


   0%	
   -­‐198	


   -­‐1%	
   	
  2.947	


   10%	
   -­‐726%	


Income	
  taxes	
   	
  1.821	


   7%	
   	
  1.753	


   6%	
   	
  2.273	


   7%	
   8%	
  
Net	
  profit	
  before	
  minority	
  interests	
   	
  3.909	


   14%	
   	
  3.947	


   14%	
   	
  6.105	


   20%	
   16%	


Minority	
  interests	
   	
  484	


   2%	
   	
  511	


   2%	
   	
  457	


   1%	
   -­‐2%	
  
Net	
  profit,	
  Group	
  share	
   	
  3.425	


   12%	
   	
  3.436	


   12%	
   	
  5.648	


   18%	
   18%	
  
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
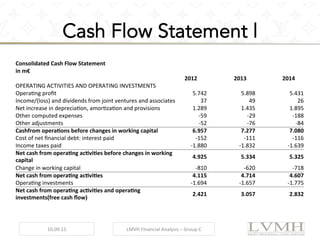
Cash Flow Statement l
Consolidated	
  Cash	
  Flow	
  Statement	


in	
  m€	


   2012	


   2013	


   2014	
  	
  
OPERATING	
  ACTIVITIES	
  AND	
  OPERATING	
  INVESTMENTS	


Operang	
  profit	
   	
  5.742	


  5.898	


  5.431	


Income/(loss)	
  and	
  dividends	
  from	
  joint	
  ventures	
  and	
  associates	
   	
  37	


  49	


  26	


Net	
  increase	
  in	
  depreciaon,	
  amorzaon	
  and	
  provisions	
   	
  1.289	


  1.435	


  1.895	


Other	
  computed	
  expenses	
   -­‐59	


   -­‐29	


   -­‐188	


Other	
  adjustments	
   -­‐52	


   -­‐76	


   -­‐84	


Cashfrom	
  operaVons	
  before	
  changes	
  in	
  working	
  capital	
   	
  6.957	


  7.277	


  7.080	


Cost	
  of	
  net	
  financial	
  debt:	
  interest	
  paid	
   -­‐152	


   -­‐111	


   -­‐116	


Income	
  taxes	
  paid	
   -­‐1.880	


   -­‐1.832	


   -­‐1.639	


Net	
  cash	
  from	
  operaVng	
  acVviVes	
  before	
  changes	
  in	
  working	
  
capital	
  
	
  4.925	


  5.334	


  5.325	


Change	
  in	
  working	
  capital	
   -­‐810	


   -­‐620	


   -­‐718	


Net	
  cash	
  from	
  operaVng	
  acVviVes	
   	
  4.115	


  4.714	


  4.607	


Operang	
  investments	
   -­‐1.694	


   -­‐1.657	


   -­‐1.775	


Net	
  cash	
  from	
  operaVng	
  acVviVes	
  and	
  operaVng	
  
investments(free	
  cash	
  flow)	
  
	
  2.421	


  3.057	


  2.832	


10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
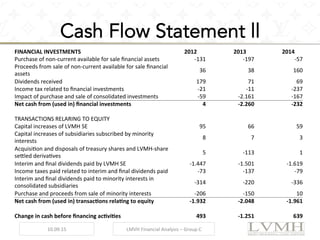
Cash Flow Statement ll
FINANCIAL	
  INVESTMENTS	
   	
  2012	


  2013	


  2014	
  
Purchase	
  of	
  non-­‐current	
  available	
  for	
  sale	
  financial	
  assets	
   -­‐131	


   -­‐197	


   -­‐57	


Proceeds	
  from	
  sale	
  of	
  non-­‐current	
  available	
  for	
  sale	
  financial	
  
assets	
  
	
  36	


  38	


  160	


Dividends	
  received	
   	
  179	


  71	


  69	


Income	
  tax	
  related	
  to	
  financial	
  investments	
   -­‐21	


   -­‐11	


   -­‐237	


Impact	
  of	
  purchase	
  and	
  sale	
  of	
  consolidated	
  investments	
   -­‐59	


   -­‐2.161	


   -­‐167	


Net	
  cash	
  from	
  (used	
  in)	
  financial	
  investments	
   	
  4	


   -­‐2.260	


   -­‐232	


TRANSACTIONS	
  RELARING	
  TO	
  EQUITY	


Capital	
  increases	
  of	
  LVMH	
  SE	
   	
  95	


  66	


  59	


Capital	
  increases	
  of	
  subsidiaries	
  subscribed	
  by	
  minority	
  
interests	
  
	
  8	


  7	


  3	


Acquision	
  and	
  disposals	
  of	
  treasury	
  shares	
  and	
  LVMH-­‐share	
  
se[led	
  derivaves	
  
	
  5	


   -­‐113	


  1	


Interim	
  and	
  final	
  dividends	
  paid	
  by	
  LVMH	
  SE	
   -­‐1.447	


   -­‐1.501	


   -­‐1.619	


Income	
  taxes	
  paid	
  related	
  to	
  interim	
  and	
  final	
  dividends	
  paid	
   -­‐73	


   -­‐137	


   -­‐79	


Interim	
  and	
  final	
  dividends	
  paid	
  to	
  minority	
  interests	
  in	
  
consolidated	
  subsidiaries	
  
-­‐314	


   -­‐220	


   -­‐336	


Purchase	
  and	
  proceeds	
  from	
  sale	
  of	
  minority	
  interests	
   -­‐206	


   -­‐150	


  10	


Net	
  cash	
  from	
  (used	
  in)	
  transacVons	
  relaVng	
  to	
  equity	
   -­‐1.932	


   -­‐2.048	


   -­‐1.961	


Change	
  in	
  cash	
  before	
  financing	
  acVviVes	
   	
  493	


   -­‐1.251	


  639	


10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
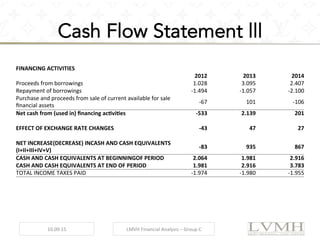
Cash Flow Statement lll
FINANCING	
  ACTIVITIES	


2012	
   2013	
   2014	
  
Proceeds	
  from	
  borrowings	
   	
  1.028	


  3.095	


  2.407	


Repayment	
  of	
  borrowings	
   -­‐1.494	


   -­‐1.057	


   -­‐2.100	


Purchase	
  and	
  proceeds	
  from	
  sale	
  of	
  current	
  available	
  for	
  sale	
  
financial	
  assets	
  
-­‐67	


  101	


   -­‐106	


Net	
  cash	
  from	
  (used	
  in)	
  financing	
  acVviVes	
   -­‐533	


  2.139	


  201	


EFFECT	
  OF	
  EXCHANGE	
  RATE	
  CHANGES	
   -­‐43	


  47	


  27	


NET	
  INCREASE(DECREASE)	
  INCASH	
  AND	
  CASH	
  EQUIVALENTS	
  
(I+II+III+IV+V)	
  
-­‐83	


  935	


  867	


CASH	
  AND	
  CASH	
  EQUIVALENTS	
  AT	
  BEGINNINGOF	
  PERIOD	
   	
  2.064	


  1.981	


  2.916	


CASH	
  AND	
  CASH	
  EQUIVALENTS	
  AT	
  END	
  OF	
  PERIOD	
   	
  1.981	


  2.916	


  3.783	


TOTAL	
  INCOME	
  TAXES	
  PAID	
   -­‐1.974	


   -­‐1.980	


   -­‐1.955	


10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
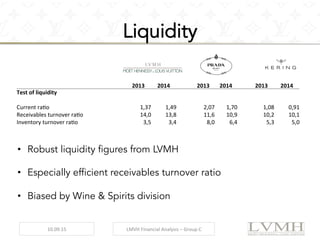
Liquidity
	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
  
Test	
  of	
  liquidity	


Current	
  rao	
   1,37	
   1,49	
  	
  	
   2,07	
   1,70	
  	
  	
   1,08	
   0,91	
  
Receivables	
  turnover	
  rao	
   14,0	
   13,8	
  	
  	
   11,6	
   10,9	
  	
  	
   10,2	
   10,1	
  
Inventory	
  turnover	
  rao	
   3,5	
   3,4	
  	
  	
   8,0	
   6,4	
  	
  	
   5,3	
   5,0	
  
•  Robust liquidity figures from LVMH
•  Especially efficient receivables turnover ratio
•  Biased by Wine & Spirits division
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Solvency
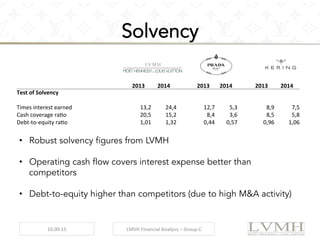
•  Robust solvency figures from LVMH
•  Operating cash flow covers interest expense better than
competitors
•  Debt-to-equity higher than competitors (due to high M&A activity)
	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
  
Test	
  of	
  Solvency	


Times	
  interest	
  earned	
   13,2	
   24,4	
   	
  	
   12,7	
   5,3	
   	
  	
   8,9	
   7,5	
  
Cash	
  coverage	
  rao	
   20,5	
   15,2	
   	
  	
   8,4	
   3,6	
   	
  	
   8,5	
   5,8	
  
Debt-­‐to-­‐equity	
  rao	
   1,01	
   1,32	
  	
  	
   0,44	
   0,57	
  	
  	
   0,96	
   1,06	
  
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Fixed Asset Analysis
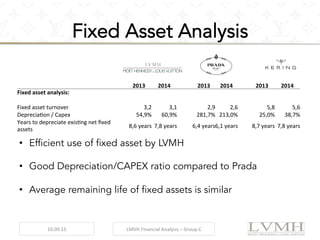
•  Efficient use of fixed asset by LVMH
•  Good Depreciation/CAPEX ratio compared to Prada
•  Average remaining life of fixed assets is similar
	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
  
Fixed	
  asset	
  analysis:	


Fixed	
  asset	
  turnover	
   3,2	
   3,1	
  	
  	
   2,9	
   2,6	
  	
  	
   5,8	
   5,6	
  
Depreciaon	
  /	
  Capex	
   54,9%	
   60,9%	
  	
  	
   281,7%	
   213,0%	
  	
  	
   25,0%	
   38,7%	
  
Years	
  to	
  depreciate	
  exisng	
  net	
  fixed	
  
assets	
  
8,6	
  years	
   7,8	
  years	
  	
  	
   6,4	
  years	
  6,1	
  years	
  	
  	
   8,7	
  years	
   7,8	
  years	
  
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Operating Ratios
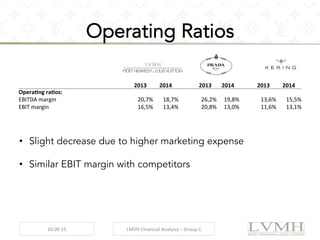
•  Slight decrease due to higher marketing expense
•  Similar EBIT margin with competitors
	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
  
OperaVng	
  raVos:	


EBITDA	
  margin	
   20,7%	
   18,7%	
  	
  	
   26,2%	
   19,8%	
  	
  	
   13,6%	
   15,5%	
  
EBIT	
  margin	
   16,5%	
   13,4%	
  	
  	
   20,8%	
   13,0%	
  	
  	
   11,6%	
   13,1%	
  
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
ROA Analysis
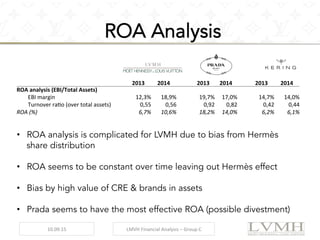
•  ROA analysis is complicated for LVMH due to bias from Hermès
share distribution
•  ROA seems to be constant over time leaving out Hermès effect
•  Bias by high value of CRE & brands in assets
•  Prada seems to have the most effective ROA (possible divestment)
	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
  
ROA	
  analysis	
  (EBI/Total	
  Assets)	


  EBI	
  margin	
   12,3%	
   18,9%	
  	
  	
   19,7%	
   17,0%	
  	
  	
   14,7%	
   14,0%	


  Turnover	
  rao	
  (over	
  total	
  assets)	
   0,55	
   0,56	
  	
  	
   0,92	
   0,82	
  	
  	
   0,42	
   0,44	
  
ROA	
  (%)	
   6,7%	
   10,6%	
  	
  	
   18,2%	
   14,0%	
  	
  	
   6,2%	
   6,1%	
  
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
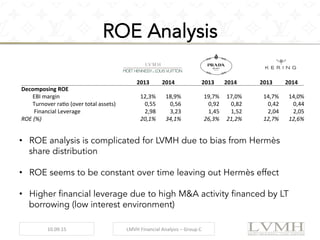
ROE Analysis
•  ROE analysis is complicated for LVMH due to bias from Hermès
share distribution
•  ROE seems to be constant over time leaving out Hermès effect
•  Higher financial leverage due to high M&A activity financed by LT
borrowing (low interest environment)
	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
  
Decomposing	
  ROE	


  EBI	
  margin	
   12,3%	
   18,9%	
  	
  	
   19,7%	
   17,0%	
  	
  	
   14,7%	
   14,0%	


  Turnover	
  rao	
  (over	
  total	
  assets)	
   0,55	
   0,56	
  	
  	
   0,92	
   0,82	
  	
  	
   0,42	
   0,44	


  Financial	
  Leverage	
   2,98	
   3,23	
  	
  	
   1,45	
   1,52	
  	
  	
   2,04	
   2,05	
  
ROE	
  (%)	
   20,1%	
   34,1%	
  	
  	
   26,3%	
   21,2%	
  	
  	
   12,7%	
   12,6%	
  
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
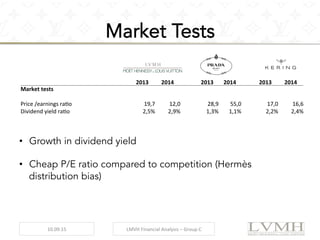
Market Tests
•  Growth in dividend yield
•  Cheap P/E ratio compared to competition (Hermès
distribution bias)


   2013	
   2014	
   	
  	
   2013	
   2014	
   	
  	
   2013	
   2014	
  
Market	
  tests	


Price	
  /earnings	
  rao	
   19,7	
   12,0	
   	
  	
   28,9	
   55,0	
   	
  	
   17,0	
   16,6	
  
Dividend	
  yield	
  rao	
   2,5%	
   2,9%	
   	
  	
   1,3%	
   1,1%	
   	
  	
   2,2%	
   2,4%	
  
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C	
  
Conclusion
•  Strong liquidity & solvency
•  Clear effect on FS of M&A activity
•  Highly profitable business
•  Impressive numbers for a steadily growing luxury
conglomerate of that size
10.09.15	
   LMVH	
  Financial	
  Analysis	
  –	
  Group	
  C