Saltar al contenido principal
Jacob Barrett, Marlon Fader, Bektemir Ysmailov
BAFN 379 FALL 2014 | UNIVERSITYOF NORTHERN COLORADO
PepsiCo Inc.
ANALYSIS PROJECT
1
Table Of Contents
Executive Summary……………………………………………………………………………………………………2
Business Description………………………………………………………………………………………………….3
Economic Analysis & Outlook…………………………………………………………………………………….4
Industry Overview and Competitive Positioning…………………………………………………..…….6
Valuation…………………………………………………………………………………………………………………10
Financial Analysis…………………………………………………………………………………………………….12
SWOT Analysis…………………………………………………………………………………………………………13
Corporate Governance and SocialResponsibility………………………………………………………14
Investment Risks & Upside Potential………………………………………………………………………..15
Project Reflection…………………………………………………………………………………………………….15
Appendices………………………………………………………………………………………………………………17
 Discounted Dividend Model…………………………………………………………………………17
 Relative Valuation………………………………………………………………………………………..19
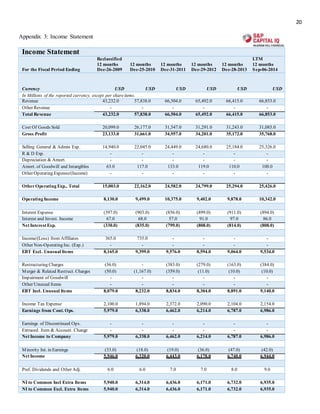
 Income Statement……………………………………………………………………………………….20
 Balance Sheet………………………………………………………………………………………………22
 Cash Flow Statement……………………………………………………………………………………24
 Common Size Income Sheet………………………………………………………………………….25
References………………………………………………………………………………………………………………27
2
Executive Summary
We issue a BUY recommendation on PepsiCo (PEP) based on an estimated fair
price of USD109.90 using Discounted Dividend Model and Relative P/E Valuation.
This implies a 9.5% upside from its closing price of USD100.39 on December 2nd
,
2014. PEP has a highly diversified portfolio in beverage and food industry which
positions it well relative to its competitors. The company has many opportunities in
the emerging and developing markets around the world as well as in new product
categories based on changing consumer tastes towards more healthy products.
Brand Recognition and Brand Building
PepsiCo is the largest food and beverage business in the United States. It is the
second largest beverage company in the world behind only Coca-Cola and the
number one distributor of salty snacks. Its current brand recognition can be
attributed to its aggressive marketing which continues to build brand awareness.
Commercials, social responsibility and athlete/celebrity endorsements are just a few
methods used by the PepsiCo marketing team. With its continued investments in
marketing PepsiCo market share is likely to continue to grow.
Position in Emerging/Developing Markets
PepsiCo generates 49% of its revenue internationally. Recently growth in emerging
markets such as India, China, Brazil, and developing nations such as Russia and
Mexico are outpacing that of developed nations such as the United States. Although
the international beverage industry is saturating, the salty snacks industry is
relatively untapped. PepsiCo revenue from emerging/developing markets today is
triple of what it was in 2006. PepsiCo management plans on continuing expansions
and expects its revenue from emerging/developing markets to eventually be two-
thirds of the total revenue.
Product Mix and Innovation
PepsiCo has a diverse portfolio of marketed products some of the bigger names
include well-known brands such as Pepsi, Mountain Dew, Gatorade, Lays Cheetos,
and Quaker. PepsiCo has 22 products that individually generate over a billion dollars
of revenue per year. They have a variety of products to attract many different
demographics. PepsiCo’s nutritious products currently make up 20% of their overall
revenue. In 2013, PepsiCo was the industry leader in successful product launches.
The company continues to broaden its product mix for both domestic and
international demographics to stimulate sales, revenue, and growth.
Market Profile
Closing Price (USD) 100.39
52-Week Price Range (USD) 77.01-
100.7
Average Daily Volume
(mm)
3.89
Shares Outstanding (mm) 1,496.60
Market Cap (USD Millions) 150,244.30
Dividend Yield 2.60%
P/E 22x
EV/EBITDA 13.2
Sources: Capital IQ
Target Price Breakdown
DDM(1) Price 107.8
DDM(2) Price 119.4
Weighted DDMPrice 113.6
P/E (1) Price 103.2
P/E (2) Price 109.2
Weighted P/E Price 106.2
Weighted Fair Price 12/14 109.9
Source: Team Estimates
Key Financial Ratios
2009 2010 2011 2012 2013 2014
Return on Equity % 39.8% 32.6% 30.5% 28.7% 29.0% 30.6%
EBIT Margin % 18.8% 16.4% 15.6% 14.4% 14.9% 15.5%
Net Income Margin % 13.8% 10.9% 9.7% 9.4% 10.1% 10.4%
FixedAsset Turnover 3.6x 3.6x 3.4x 3.4x 3.5x 3.7x
Current Ratio 1.4x 1.1x 1.0x 1.1x 1.2x 1.2x
LT Debt/Capital 29.2% 43.1% 43.1% 46.4% 45.0% 42.0%
EBIT / Interest Exp. 20.5x 10.5x 12.1x 10.5x 10.8x 11.6x
EPS $3.81 $3.97 $4.08 $3.96 $4.37 $4.57
0
1
2
3
2009 2010 2011 2012 2013 2014
PEP Dividends per Share
Source: Company Data
50.00
60.00
70.00
80.00
90.00
100.00
Share Price Movement
3
Business Description
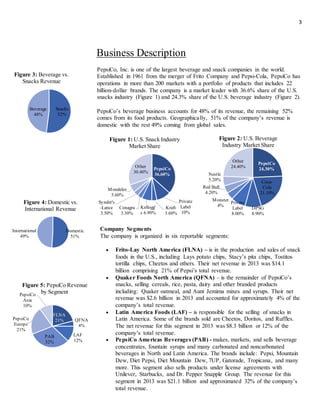
PepsiCo, Inc. is one of the largest beverage and snack companies in the world.
Established in 1961 from the merger of Frito Company and Pepsi-Cola, PepsiCo has
operations in more than 200 markets with a portfolio of products that includes 22
billion-dollar brands. The company is a market leader with 36.6% share of the U.S.
snacks industry (Figure 1) and 24.3% share of the U.S. beverage industry (Figure 2).
PepsiCo’s beverage business accounts for 48% of its revenue, the remaining 52%
comes from its food products. Geographically, 51% of the company’s revenue is
domestic with the rest 49% coming from global sales.
Company Segments
The company is organized in six reportable segments:
 Frito-Lay North America (FLNA) – is in the production and sales of snack
foods in the U.S., including Lays potato chips, Stacy’s pita chips, Tostitos
tortilla chips, Cheetos and others. Their net revenue in 2013 was $14.1
billion comprising 21% of Pepsi’s total revenue.
 Quaker Foods North America (QFNA) – is the remainder of PepsiCo’s
snacks, selling cereals, rice, pasta, dairy and other branded products
including: Quaker oatmeal, and Aunt Jemima mixes and syrups. Their net
revenue was $2.6 billion in 2013 and accounted for approximately 4% of the
company’s total revenue.
 Latin America Foods (LAF) – is responsible for the selling of snacks in
Latin America. Some of the brands sold are Cheetos, Doritos, and Ruffles.
The net revenue for this segment in 2013 was $8.3 billion or 12% of the
company’s total revenue.
 PepsiCo Americas Beverages (PAB) - makes, markets, and sells beverage
concentrates, fountain syrups and many carbonated and noncarbonated
beverages in North and Latin America. The brands include: Pepsi, Mountain
Dew, Diet Pepsi, Diet Mountain Dew, 7UP, Gatorade, Tropicana, and many
more. This segment also sells products under license agreements with
Unilever, Starbucks, and Dr. Pepper Snapple Group. The revenue for this
segment in 2013 was $21.1 billion and approximated 32% of the company’s
total revenue.
PepsiCo
24.30%
Coca-
Cola
21.10%
DPSG
8.90%
Private
Label
8.00%
Monster
4%
Red Bull
4.20%
Nestle
5.20%
Other
24.40%
Figure 2: U.S. Beverage
Industry Market Share
PepsiCo
36.60%
Private
Label
10%
Kraft
3.60%
Kellogg'
s 6.90%
Conagra
3.30%
Synder's
-Lance
3.50%
Mondelez
5.60%
Other
30.40%
Figure 1: U.S. Snack Industry
Market Share
FLNA
21% QFNA
4%
LAF
12%
PAB
32%
PepsiCo
Europe
21%
PepsiCo
Asia
10%
Figure 5: PepsiCo Revenue
by Segment
Snacks
52%
Beverage
48%
Figure 3: Beverage vs.
Snacks Revenue
Domestic
51%
International
49%
Figure 4: Domestic vs.
International Revenue
4
 PepsiCo Europe – attends to the selling of PepsiCo products in Europe, and
South Africa (SA). Europe’s net revenue was $13.8 billion in 2013 and was
21% of total revenue.
 PepsiCo Asia, Middle East and Africa (AMEA) - manages all beverage
sales, food and snack businesses in AMEA excluding SA. Their net revenue
was $6.5 billion in 2013 and approximated 10% of PepsiCo’s total revenue.
Economic Analysis and Outlook
US Economic Performance
Improving U.S. GDP Growth
The US economy has been on a steady growth path since the financial crisis of
2008-2009 with occasional disruptions caused by non-fundamental factors such as
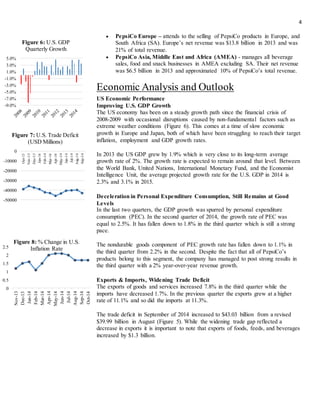
extreme weather conditions (Figure 6). This comes at a time of slow economic
growth in Europe and Japan, both of which have been struggling to reach their target
inflation, employment and GDP growth rates.
In 2013 the US GDP grew by 1.9% which is very close to its long-term average
growth rate of 2%. The growth rate is expected to remain around that level. Between
the World Bank, United Nations, International Monetary Fund, and the Economist
Intelligence Unit, the average projected growth rate for the U.S. GDP in 2014 is
2.3% and 3.1% in 2015.
Deceleration in Personal Expenditure Consumption, Still Remains at Good
Levels
In the last two quarters, the GDP growth was spurred by personal expenditure
consumption (PEC). In the second quarter of 2014, the growth rate of PEC was
equal to 2.5%. It has fallen down to 1.8% in the third quarter which is still a strong
pace.
The nondurable goods component of PEC growth rate has fallen down to 1.1% in
the third quarter from 2.2% in the second. Despite the fact that all of PepsiCo’s
products belong to this segment, the company has managed to post strong results in
the third quarter with a 2% year-over-year revenue growth.
Exports & Imports, Widening Trade Deficit
The exports of goods and services increased 7.8% in the third quarter while the
imports have decreased 1.7%. In the previous quarter the exports grew at a higher
rate of 11.1% and so did the imports at 11.3%.
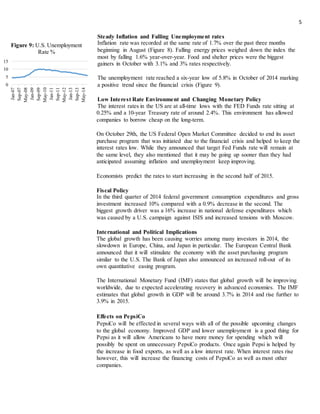
The trade deficit in September of 2014 increased to $43.03 billion from a revised
$39.99 billion in August (Figure 5). While the widening trade gap reflected a
decrease in exports it is important to note that exports of foods, feeds, and beverages
increased by $1.3 billion.
-9.0%
-7.0%
-5.0%
-3.0%
-1.0%
1.0%
3.0%
5.0%
Figure 6: U.S. GDP
Quarterly Growth
-50000
-40000
-30000
-20000
-10000
0
Oct-13
Nov-13
Dec-13
Jan-14
Feb-14
Mar-14
Apr-14
May-14
Jun-14
Jul-14
Aug-14
Sep-14
Figure 7: U.S. Trade Deficit
(USD Millions)
0
0.5
1
1.5
2
2.5
Nov-13
Dec-13
Jan-14
Feb-14
Mar-14
Apr-14
May-14
Jun-14
Jul-14
Aug-14
Sep-14
Oct-14
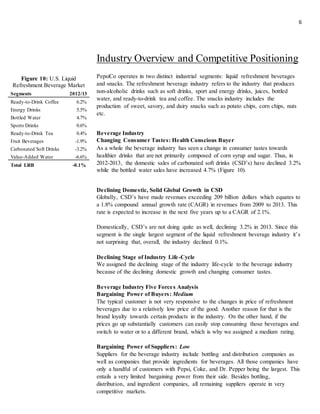
Figure 8: % Change in U.S.
Inflation Rate
5
Steady Inflation and Falling Unemployment rates
Inflation rate was recorded at the same rate of 1.7% over the past three months
beginning in August (Figure 8). Falling energy prices weighed down the index the
most by falling 1.6% year-over-year. Food and shelter prices were the biggest
gainers in October with 3.1% and 3% rates respectively.
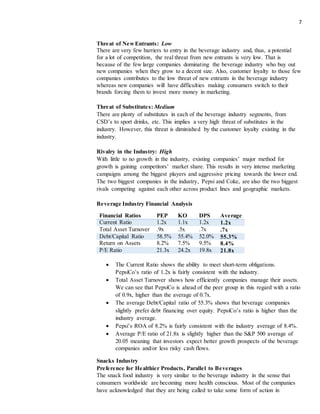
The unemployment rate reached a six-year low of 5.8% in October of 2014 marking
a positive trend since the financial crisis (Figure 9).
Low Interest Rate Environment and Changing Monetary Policy
The interest rates in the US are at all-time lows with the FED Funds rate sitting at
0.25% and a 10-year Treasury rate of around 2.4%. This environment has allowed
companies to borrow cheap on the long-term.
On October 29th, the US Federal Open Market Committee decided to end its asset
purchase program that was initiated due to the financial crisis and helped to keep the
interest rates low. While they announced that target Fed Funds rate will remain at
the same level, they also mentioned that it may be going up sooner than they had
anticipated assuming inflation and unemployment keep improving.
Economists predict the rates to start increasing in the second half of 2015.
Fiscal Policy
In the third quarter of 2014 federal government consumption expenditures and gross
investment increased 10% compared with a 0.9% decrease in the second. The
biggest growth driver was a 16% increase in national defense expenditures which
was caused by a U.S. campaign against ISIS and increased tensions with Moscow.
International and Political Implications
The global growth has been causing worries among many investors in 2014, the
slowdown in Europe, China, and Japan in particular. The European Central Bank
announced that it will stimulate the economy with the asset purchasing program
similar to the U.S. The Bank of Japan also announced an increased roll-out of its
own quantitative easing program.
The International Monetary Fund (IMF) states that global growth will be improving
worldwide, due to expected accelerating recovery in advanced economies. The IMF
estimates that global growth in GDP will be around 3.7% in 2014 and rise further to
3.9% in 2015.
Effects on PepsiCo
PepsiCo will be effected in several ways with all of the possible upcoming changes
to the global economy. Improved GDP and lower unemployment is a good thing for
Pepsi as it will allow Americans to have more money for spending which will
possibly be spent on unnecessary PepsiCo products. Once again Pepsi is helped by
the increase in food exports, as well as a low interest rate. When interest rates rise
however, this will increase the financing costs of PepsiCo as well as most other
companies.
0
5
10
15
Jan-07
Sep-07
May-08
Jan-09
Sep-09
May-10
Jan-11
Sep-11
May-12
Jan-13
Sep-13
May-14
Figure 9: U.S. Unemployment
Rate %
6
Industry Overview and Competitive Positioning
PepsiCo operates in two distinct industrial segments: liquid refreshment beverages
and snacks. The refreshment beverage industry refers to the industry that produces
non-alcoholic drinks such as soft drinks, sport and energy drinks, juices, bottled
water, and ready-to-drink tea and coffee. The snacks industry includes the
production of sweet, savory, and dairy snacks such as potato chips, corn chips, nuts
etc.
Beverage Industry
Changing Consumer Tastes: Health Conscious Buyer
As a whole the beverage industry has seen a change in consumer tastes towards
healthier drinks that are not primarily composed of corn syrup and sugar. Thus, in
2012-2013, the domestic sales of carbonated soft drinks (CSD’s) have declined 3.2%
while the bottled water sales have increased 4.7% (Figure 10).
Declining Domestic, Solid Global Growth in CSD
Globally, CSD’s have made revenues exceeding 209 billion dollars which equates to
a 1.8% compound annual growth rate (CAGR) in revenues from 2009 to 2013. This
rate is expected to increase in the next five years up to a CAGR of 2.1%.
Domestically, CSD’s are not doing quite as well, declining 3.2% in 2013. Since this
segment is the single largest segment of the liquid refreshment beverage industry it’s
not surprising that, overall, the industry declined 0.1%.
Declining Stage of Industry Life-Cycle
We assigned the declining stage of the industry life-cycle to the beverage industry
because of the declining domestic growth and changing consumer tastes.
Beverage Industry Five Forces Analysis
Bargaining Power of Buyers: Medium
The typical customer is not very responsive to the changes in price of refreshment
beverages due to a relatively low price of the good. Another reason for that is the
brand loyalty towards certain products in the industry. On the other hand, if the
prices go up substantially customers can easily stop consuming those beverages and
switch to water or to a different brand, which is why we assigned a medium rating.
Bargaining Power of Suppliers: Low
Suppliers for the beverage industry include bottling and distribution companies as
well as companies that provide ingredients for beverages. All those companies have
only a handful of customers with Pepsi, Coke, and Dr. Pepper being the largest. This
entails a very limited bargaining power from their side. Besides bottling,
distribution, and ingredient companies, all remaining suppliers operate in very
competitive markets.
Figure 10: U.S. Liquid
Refreshment Beverage Market
Segments 2012/13
Ready-to-Drink Coffee 6.2%
Energy Drinks 5.5%
Bottled Water 4.7%
Sports Drinks 0.6%
Ready-to-Drink Tea 0.4%
Fruit Beverages -1.9%
Carbonated Soft Drinks -3.2%
Value-Added Water -6.6%
Total LRB -0.1%
7
Threat of NewEntrants: Low
There are very few barriers to entry in the beverage industry and, thus, a potential
for a lot of competition, the real threat from new entrants is very low. That is
because of the few large companies dominating the beverage industry who buy out
new companies when they grow to a decent size. Also, customer loyalty to those few
companies contributes to the low threat of new entrants in the beverage industry
whereas new companies will have difficulties making consumers switch to their
brands forcing them to invest more money in marketing.
Threat of Substitutes: Medium
There are plenty of substitutes in each of the beverage industry segments, from
CSD’s to sport drinks, etc. This implies a very high threat of substitutes in the
industry. However, this threat is diminished by the customer loyalty existing in the
industry.
Rivalry in the Industry: High
With little to no growth in the industry, existing companies’ major method for
growth is gaining competitors’ market share. This results in very intense marketing
campaigns among the biggest players and aggressive pricing towards the lower end.
The two biggest companies in the industry, Pepsi and Coke, are also the two biggest
rivals competing against each other across product lines and geographic markets.
Beverage Industry Financial Analysis
Financial Ratios PEP KO DPS Average
Current Ratio 1.2x 1.1x 1.2x 1.2x
Total Asset Turnover .9x .5x .7x .7x
Debt/Capital Ratio 58.5% 55.4% 52.0% 55.3%
Return on Assets 8.2% 7.5% 9.5% 8.4%
P/E Ratio 21.3x 24.2x 19.8x 21.8x
 The Current Ratio shows the ability to meet short-term obligations.
PepsiCo’s ratio of 1.2x is fairly consistent with the industry.
 Total Asset Turnover shows how efficiently companies manage their assets.
We can see that PepsiCo is ahead of the peer group in this regard with a ratio
of 0.9x, higher than the average of 0.7x.
 The average Debt/Capital ratio of 55.3% shows that beverage companies
slightly prefer debt financing over equity. PepsiCo’s ratio is higher than the
industry average.
 Pepsi’s ROA of 8.2% is fairly consistent with the industry average of 8.4%.
 Average P/E ratio of 21.8x is slightly higher than the S&P 500 average of
20.05 meaning that investors expect better growth prospects of the beverage
companies and/or less risky cash flows.
Snacks Industry
Preference for Healthier Products, Parallel to Beverages
The snack food industry is very similar to the beverage industry in the sense that
consumers worldwide are becoming more health conscious. Most of the companies
have acknowledged that they are being called to take some form of action in
8
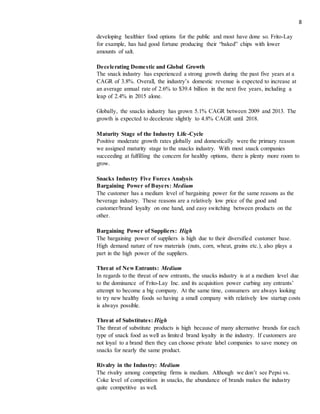
developing healthier food options for the public and most have done so. Frito-Lay
for example, has had good fortune producing their “baked” chips with lower
amounts of salt.
Decelerating Domestic and Global Growth
The snack industry has experienced a strong growth during the past five years at a
CAGR of 3.8%. Overall, the industry’s domestic revenue is expected to increase at
an average annual rate of 2.6% to $39.4 billion in the next five years, including a
leap of 2.4% in 2015 alone.
Globally, the snacks industry has grown 5.1% CAGR between 2009 and 2013. The
growth is expected to decelerate slightly to 4.8% CAGR until 2018.
Maturity Stage of the Industry Life-Cycle
Positive moderate growth rates globally and domestically were the primary reason
we assigned maturity stage to the snacks industry. With most snack companies
succeeding at fulfilling the concern for healthy options, there is plenty more room to
grow.
Snacks Industry Five Forces Analysis
Bargaining Power of Buyers: Medium
The customer has a medium level of bargaining power for the same reasons as the
beverage industry. These reasons are a relatively low price of the good and
customer/brand loyalty on one hand, and easy switching between products on the
other.
Bargaining Power of Suppliers: High
The bargaining power of suppliers is high due to their diversified customer base.
High demand nature of raw materials (nuts, corn, wheat, grains etc.), also plays a
part in the high power of the suppliers.
Threat of New Entrants: Medium
In regards to the threat of new entrants, the snacks industry is at a medium level due
to the dominance of Frito-Lay Inc. and its acquisition power curbing any entrants’
attempt to become a big company. At the same time, consumers are always looking
to try new healthy foods so having a small company with relatively low startup costs
is always possible.
Threat of Substitutes: High
The threat of substitute products is high because of many alternative brands for each
type of snack food as well as limited brand loyalty in the industry. If customers are
not loyal to a brand then they can choose private label companies to save money on
snacks for nearly the same product.
Rivalry in the Industry: Medium
The rivalry among competing firms is medium. Although we don’t see Pepsi vs.
Coke level of competition in snacks, the abundance of brands makes the industry
quite competitive as well.
9
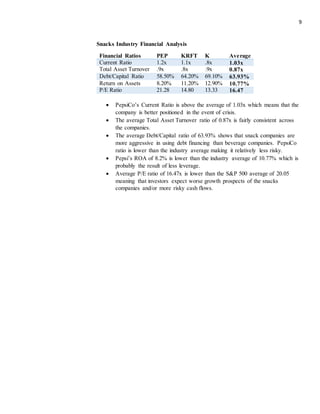
Snacks Industry Financial Analysis
Financial Ratios PEP KRFT K Average
Current Ratio 1.2x 1.1x .8x 1.03x
Total Asset Turnover .9x .8x .9x 0.87x
Debt/Capital Ratio 58.50% 64.20% 69.10% 63.93%
Return on Assets 8.20% 11.20% 12.90% 10.77%
P/E Ratio 21.28 14.80 13.33 16.47
 PepsiCo’s Current Ratio is above the average of 1.03x which means that the
company is better positioned in the event of crisis.
 The average Total Asset Turnover ratio of 0.87x is fairly consistent across
the companies.
 The average Debt/Capital ratio of 63.93% shows that snack companies are
more aggressive in using debt financing than beverage companies. PepsiCo
ratio is lower than the industry average making it relatively less risky.
 Pepsi’s ROA of 8.2% is lower than the industry average of 10.77% which is
probably the result of less leverage.
 Average P/E ratio of 16.47x is lower than the S&P 500 average of 20.05
meaning that investors expect worse growth prospects of the snacks
companies and/or more risky cash flows.
10
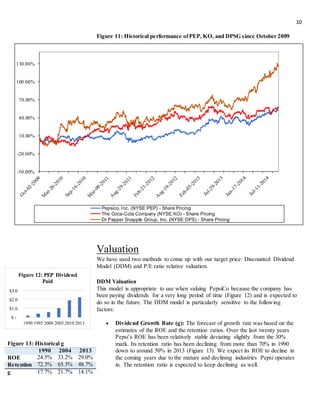
Figure 11: Historical performance ofPEP, KO, and DPSG since October 2009
Valuation
We have used two methods to come up with our target price: Discounted Dividend
Model (DDM) and P/E ratio relative valuation.
DDM Valuation
This model is appropriate to use when valuing PepsiCo because the company has
been paying dividends for a very long period of time (Figure 12) and is expected to
do so in the future. The DDM model is particularly sensitive to the following
factors:
 Dividend Growth Rate (g): The forecast of growth rate was based on the
estimates of the ROE and the retention ratios. Over the last twenty years
Pepsi’s ROE has been relatively stable deviating slightly from the 30%
mark. Its retention ratio has been declining from more than 70% in 1990
down to around 50% in 2013 (Figure 13). We expect its ROE to decline in
the coming years due to the mature and declining industries Pepsi operates
in. The retention ratio is expected to keep declining as well.
Figure 13: Historical g
1990 2004 2013
ROE 24.5% 33.2% 29.0%
Retention 72.3% 65.3% 48.7%
g 17.7% 21.7% 14.1%
$ -
$1.0
$2.0
$3.0
1990 1995 2000 2005 2010 2013
Figure 12: PEP Dividend
Paid
-50.00%
-20.00%
10.00%
40.00%
70.00%
100.00%
130.00%
Pepsico, Inc. (NYSE:PEP) - Share Pricing
The Coca-Cola Company (NYSE:KO) - Share Pricing
Dr Pepper Snapple Group, Inc. (NYSE:DPS) - Share Pricing
11
2015 - 2020E 2021 - 2030E 2030+E
ROE 25% 15%
Retention 40% 30%
g 10.00% 4.50% 2%
 Terminal Growth Rate: We decided to use a 2% terminal growth rate
because of PepsiCo’s consistently good performance in the past, as well as
potential in emerging markets.
 Risk Free Rate (Rf): For the risk free rate we used an approximate 10-year
treasury rate of 2.5% for the next two years (2015 - 2016). For the years
2017+ we decided to use a slightly higher 3.5% rate to account for the
expected rise in interest rates.
 Market Risk Premium (Rm-Rf): The market risk premium of 5% given in
the outline seemed appropriate in our case.
 Computations: Using the capital asset pricing model and the values in
Figure 14 we attained a required rate of return of 5.3% in 2015-2016, and
6.3% from 2017 on. Our final fair price value for our DDM model was an
average of our bullish and bearish scenarios resulting in a value of
USD113.60.
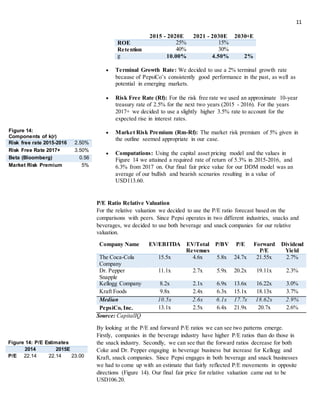
P/E Ratio Relative Valuation
For the relative valuation we decided to use the P/E ratio forecast based on the
comparisons with peers. Since Pepsi operates in two different industries, snacks and
beverages, we decided to use both beverage and snack companies for our relative
valuation.
Company Name EV/EBITDA EV/Total
Revenues
P/BV P/E Forward
P/E
Dividend
Yield
The Coca-Cola
Company
15.5x 4.6x 5.8x 24.7x 21.55x 2.7%
Dr. Pepper
Snapple
11.1x 2.7x 5.9x 20.2x 19.11x 2.3%
Kellogg Company 8.2x 2.1x 6.9x 13.6x 16.22x 3.0%
Kraft Foods 9.8x 2.4x 6.3x 15.1x 18.13x 3.7%
Median 10.5x 2.6x 6.1x 17.7x 18.62x 2.9%
PepsiCo, Inc. 13.1x 2.5x 6.4x 21.9x 20.7x 2.6%
Source: CapitalIQ
By looking at the P/E and forward P/E ratios we can see two patterns emerge.
Firstly, companies in the beverage industry have higher P/E ratios than do those in
the snack industry. Secondly, we can see that the forward ratios decrease for both
Coke and Dr. Pepper engaging in beverage business but increase for Kellogg and
Kraft, snack companies. Since Pepsi engages in both beverage and snack businesses
we had to come up with an estimate that fairly reflected P/E movements in opposite
directions (Figure 14). Our final fair price for relative valuation came out to be
USD106.20.
Figure 14:
Components of k(r)
Risk free rate 2015-2016 2.50%
Risk Free Rate 2017+ 3.50%
Beta (Bloomberg) 0.56
Market Risk Premium 5%
Figure 14: P/E Estimates
2014 2015E
P/E 22.14 22.14 23.00
12
An average of the DDM price, USD113.60, and the relative P/E price, USD106.20,
gave us the final value of USD109.90. (Full calculations in Appendix 1 & 2)
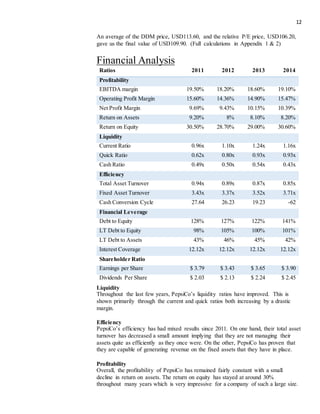
Financial Analysis
Ratios 2011 2012 2013 2014
Profitability
EBITDA margin 19.50% 18.20% 18.60% 19.10%
Operating Profit Margin 15.60% 14.36% 14.90% 15.47%
Net Profit Margin 9.69% 9.43% 10.15% 10.39%
Return on Assets 9.20% 8% 8.10% 8.20%
Return on Equity 30.50% 28.70% 29.00% 30.60%
Liquidity
Current Ratio 0.96x 1.10x 1.24x 1.16x
Quick Ratio 0.62x 0.80x 0.93x 0.93x
Cash Ratio 0.49x 0.50x 0.54x 0.43x
Efficiency
Total Asset Turnover 0.94x 0.89x 0.87x 0.85x
Fixed Asset Turnover 3.43x 3.37x 3.52x 3.71x
Cash Conversion Cycle 27.64 26.23 19.23 -62
Financial Leverage
Debt to Equity 128% 127% 122% 141%
LT Debt to Equity 98% 105% 100% 101%
LT Debt to Assets 43% 46% 45% 42%
Interest Coverage 12.12x 12.12x 12.12x 12.12x
Shareholder Ratio
Earnings per Share $ 3.79 $ 3.43 $ 3.65 $ 3.90
Dividends Per Share $ 2.03 $ 2.13 $ 2.24 $ 2.45
Liquidity
Throughout the last few years, PepsiCo’s liquidity ratios have improved. This is
shown primarily through the current and quick ratios both increasing by a drastic
margin.
Efficiency
PepsiCo’s efficiency has had mixed results since 2011. On one hand, their total asset
turnover has decreased a small amount implying that they are not managing their
assets quite as efficiently as they once were. On the other, PepsiCo has proven that
they are capable of generating revenue on the fixed assets that they have in place.
Profitability
Overall, the profitability of PepsiCo has remained fairly constant with a small
decline in return on assets. The return on equity has stayed at around 30%
throughout many years which is very impressive for a company of such a large size.
13
Debt
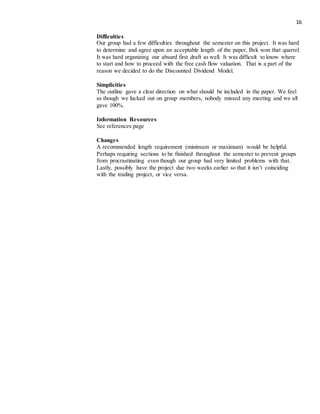
PepsiCo’s use of long-term debt has stayed relatively constant as seen by the long-
term debt to equity and to assets ratios. It’s important to note that the total debt to
equity has fluctuated more edging up to 141% in 2014 from 122% in 2013. This
implies that the company has taken out short-term financing which in theory should
worsen PepsiCo’s liquidity but wasn’t the case in reality as the liquidity improved,
discussed earlier.
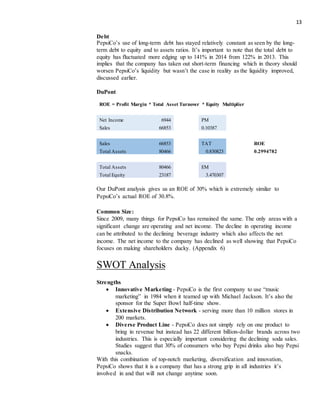
DuPont
ROE = Profit Margin * Total Asset Turnover * Equity Multiplier
Net Income 6944 PM
Sales 66853 0.10387
Sales 66853 TAT ROE
Total Assets 80466 0.830823 0.2994782
Total Assets 80466 EM
Total Equity 23187 3.470307
Our DuPont analysis gives us an ROE of 30% which is extremely similar to
PepsiCo’s actual ROE of 30.8%.
Common Size:
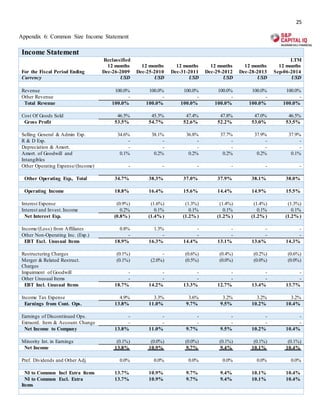
Since 2009, many things for PepsiCo has remained the same. The only areas with a
significant change are operating and net income. The decline in operating income
can be attributed to the declining beverage industry which also affects the net
income. The net income to the company has declined as well showing that PepsiCo
focuses on making shareholders ducky. (Appendix 6)
SWOT Analysis
Strengths
 Innovative Marketing - PepsiCo is the first company to use “music
marketing” in 1984 when it teamed up with Michael Jackson. It’s also the
sponsor for the Super Bowl half-time show.
 Extensive Distribution Network - serving more than 10 million stores in
200 markets.
 Diverse Product Line - PepsiCo does not simply rely on one product to
bring in revenue but instead has 22 different billion-dollar brands across two
industries. This is especially important considering the declining soda sales.
Studies suggest that 30% of consumers who buy Pepsi drinks also buy Pepsi
snacks.
With this combination of top-notch marketing, diversification and innovation,
PepsiCo shows that it is a company that has a strong grip in all industries it’s
involved in and that will not change anytime soon.
14
Weaknesses
 Profitability - PepsiCo’s profit margin has recently been lower than that of
its main competitors. This means that if the company wants to increase its
profitability it needs either to increase prices which can result in lost
customers or to decrease its costs which can potentially hurt the product
quality.
 Unhealthy Product Portfolio – As of today the product portfolio of
PepsiCo is mostly unhealthy. It’s important that the company keeps up with
the trend of changing consumer tastes.
Opportunities
 Emerging and Developing Markets - PepsiCo realizes that some of their
biggest opportunities lie in emerging and developing markets. Specifically
Pepsi is investing in China and India. Currently 51% of PepsiCo sales are
generated domestically.
 New Products for Health Conscious Consumer - As consumer desire for
healthier snacks and beverages is increasing so do opportunities for PepsiCo
to enter these new industry segments through new ventures. Besides that,
with PepsiCo’s substantial amount of capital power there are always more
opportunities for them to increase market share through mergers and
acquisitions.
Threats
 Competitors - Although PepsiCo is one of the dominant companies in its
industries, it does have a few competitors, Coca Cola, Dr. Pepper, Kraft, and
Kellogg are always a threat to Pepsi's market share.
 Regulation - U.S government is considering passing legislation that would
force PepsiCo to disclose ingredients for some of its products that, as
research suggests, may cause cancer.
 Changing Consumer Taste - Another threat is that consumer tastes are
changing, they are becoming more health conscious therefore reducing their
purchases of snacks and carbonated beverages.
CorporateGovernance and Social Responsibility
Corporate Governance
PepsiCo has strict corporate standards that govern their operations. The rules,
expectations and duties are outlined in the Corporate Governance Guidelines which
are readily available on PepsiCo’s official website. The company has three
committee charters: Audit, Compensation, and Nominating & Corporate
Governance Committees. All statements and policies are available online which
shows the company’s commitment to transparency.
Corporate Social Responsibility
All of PepsiCo’s corporate social responsibilities (CSR’s) activities are outlined in
the latest Sustainability Report. Some of the highlights include:
 Recently the company received 100% rating on the corporate equality index
released by the LGBT human rights group campaign.
15
 Since 1962 Pepsi is running a charitable program called PepsiCo Foundation
which primarily focuses on nutrition, activity, safe water and water usages.
They have given grants to programs such as the YMCA and United Way
among others. The Foundation has helped 3 million people gain access to
safe water as of 2013 and plans on doubling that by 2015.
 PepsiCo realizes that environmental sustainability is becoming more and
more parallel to sustainable success. Therefore plans are being put in place
for developing systems to improve conservation. In the 2013 sustainability
report, the company outlines its plans to eliminate waste from production
facilities, implement innovative recyclable packaging, and protect and
conserve water supplies.
Investment Risks and Upside Potential
Downside Risks
Along with the ordinary risks that a company goes through (tax increases,
unfavorable economic conditions, failure to compete effectively, etc.), PepsiCo has a
unique set of investment risks.
Operational Risk│ Inability to Grow in Emerging and Developing Markets
There are a number of reasons that PepsiCo would not be able to expand to
emerging markets that include unstable political conditions, civil unrest, and other
developmental hazards. However, even if PepsiCo expands into other countries there
is no guarantee that products will be enjoyed or purchased overseas due to cultural
differences.
Operational Risk│Change in Consumer Tastes
As mentioned throughout, consumer tastes in the last few years have changed
drastically which already makes a stir in PepsiCo’s operations. In order to stay in
business and make a profit they have had to adjust their products. PepsiCo says that
their success depends on the, “ability to anticipate and respond to shifts in consumer
trends,” which does include health concerns.
Market Risk│Fluctuations in Exchange Rates
Being a global giant in beverage and snacking, PepsiCo is very tangled with
exchange rates throughout Europe and Latin America. With financial statements
being presented in U.S. dollars, wavering exchange rates could have a negative or
positive effect on the company’s financials.
Project Reflection
Learning
We all felt like we learned a great deal working on this project. The things we
learned ranged from analyzing companies from their ratios, to valuing a company
using mathematics. It absolutely helped us in applying the financial concepts learned
in class to a real world report. Lastly, we learned to understand the importance of
communication as a group.
16
Difficulties
Our group had a few difficulties throughout the semester on this project. It was hard
to determine and agree upon an acceptable length of the paper, Bek won that quarrel.
It was hard organizing our absurd first draft as well. It was difficult to know where
to start and how to proceed with the free cash flow valuation. That is a part of the
reason we decided to do the Discounted Dividend Model.
Simplicities
The outline gave a clear direction on what should be included in the paper. We feel
as though we lucked out on group members, nobody missed any meeting and we all
gave 100%.
Information Resources
See references page
Changes
A recommended length requirement (minimum or maximum) would be helpful.
Perhaps requiring sections to be finished throughout the semester to prevent groups
from procrastinating even though our group had very limited problems with that.
Lastly, possibly have the project due two weeks earlier so that it isn’t coinciding
with the trading project, or vice versa.
17
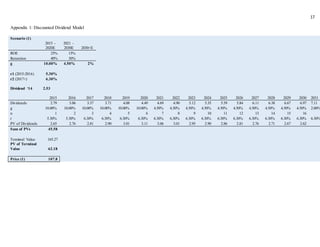
Appendix 1: Discounted Dividend Model
Scenario (1)
2015 -
2020E
2021 -
2030E 2030+E
ROE 25% 15%
Retention 40% 30%
g 10.00% 4.50% 2%
r1 (2015-2016) 5.30%
r2 (2017+) 6.30%
Dividend ‘14 2.53
2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027 2028 2029 2030 2031
Dividends 2.79 3.06 3.37 3.71 4.08 4.49 4.69 4.90 5.12 5.35 5.59 5.84 6.11 6.38 6.67 6.97 7.11
g 10.00% 10.00% 10.00% 10.00% 10.00% 10.00% 4.50% 4.50% 4.50% 4.50% 4.50% 4.50% 4.50% 4.50% 4.50% 4.50% 2.00%
n 1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16
r 5.30% 5.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30%
PV of Dividends 2.65 2.76 2.81 2.90 3.01 3.11 3.06 3.01 2.95 2.90 2.86 2.81 2.76 2.71 2.67 2.62
Sum of PVs 45.58
Terminal Value 165.27
PV of Terminal
Value 62.18
Price (1) 107.8
18
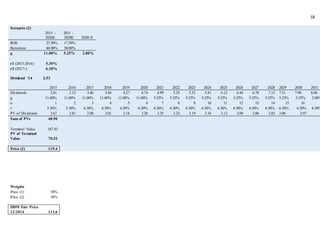
Scenario (2)
2015 -
2020E
2021 -
2030E 2030+E
ROE 27.50% 17.50%
Retention 40.00% 30.00%
g 11.00% 5.25% 2.00%
r1 (2015-2016) 5.30%
r2 (2017+) 6.30%
Dividend ‘14 2.53
2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027 2028 2029 2030 2031
Dividends 2.81 3.12 3.46 3.84 4.27 4.74 4.99 5.25 5.52 5.81 6.12 6.44 6.78 7.13 7.51 7.90 8.06
g 11.00% 11.00% 11.00% 11.00% 11.00% 11.00% 5.25% 5.25% 5.25% 5.25% 5.25% 5.25% 5.25% 5.25% 5.25% 5.25% 2.00%
n 1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16
r 5.30% 5.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30% 6.30%
PV of Dividends 2.67 2.81 2.88 3.01 3.14 3.28 3.25 3.22 3.19 3.16 3.12 3.09 3.06 3.03 3.00 2.97
Sum of PVs 48.90
Terminal Value 187.43
PV of Terminal
Value 70.52
Price (2) 119.4
Weights
Price (1) 50%
Price (2) 50%
DDM Fair Price
12/2014 113.6
19
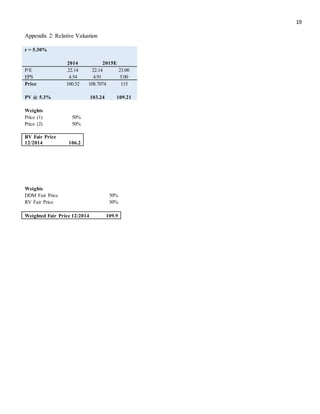
Appendix 2: Relative Valuation
r = 5.30%
2014 2015E
P/E 22.14 22.14 23.00
EPS 4.54 4.91 5.00
Price 100.52 108.7074 115
PV @ 5.3% 103.24 109.21
Weights
Price (1) 50%
Price (2) 50%
RV Fair Price
12/2014 106.2
Weights
DDM Fair Price 50%
RV Fair Price 50%
Weighted Fair Price 12/2014 109.9
20
Appendix 3: Income Statement
Income Statement
For the Fiscal Period Ending
Reclassified
12 months
Dec-26-2009
12 months
Dec-25-2010
12 months
Dec-31-2011
12 months
Dec-29-2012
12 months
Dec-28-2013
LTM
12 months
Sep-06-2014
Currency USD USD USD USD USD USD
In Millions of the reported currency, except per shareitems.
Revenue 43,232.0 57,838.0 66,504.0 65,492.0 66,415.0 66,853.0
Other Revenue - - - - - -
Total Revenue 43,232.0 57,838.0 66,504.0 65,492.0 66,415.0 66,853.0
Cost Of Goods Sold 20,099.0 26,177.0 31,547.0 31,291.0 31,243.0 31,085.0
Gross Profit 23,133.0 31,661.0 34,957.0 34,201.0 35,172.0 35,768.0
Selling General & Admin Exp. 14,940.0 22,045.0 24,449.0 24,680.0 25,184.0 25,326.0
R & D Exp. - - - - - -
Depreciation & Amort. - - - - - -
Amort. of Goodwill and Intangibles 63.0 117.0 133.0 119.0 110.0 100.0
Other Operating Expense/(Income) - - - - - -
OtherOperating Exp., Total 15,003.0 22,162.0 24,582.0 24,799.0 25,294.0 25,426.0
Operating Income 8,130.0 9,499.0 10,375.0 9,402.0 9,878.0 10,342.0
Interest Expense (397.0) (903.0) (856.0) (899.0) (911.0) (894.0)
Interest and Invest. Income 67.0 68.0 57.0 91.0 97.0 86.0
Net Interest Exp. (330.0) (835.0) (799.0) (808.0) (814.0) (808.0)
Income/(Loss) from Affiliates 365.0 735.0 - - - -
Other Non-Operating Inc. (Exp.) - - - - - -
EBT Excl. Unusual Items 8,165.0 9,399.0 9,576.0 8,594.0 9,064.0 9,534.0
Restructuring Charges (36.0) - (383.0) (279.0) (163.0) (384.0)
Merger & Related Restruct. Charges (50.0) (1,167.0) (359.0) (11.0) (10.0) (10.0)
Impairment of Goodwill - - - - - -
Other Unusual Items - - - - - -
EBT Incl. Unusual Items 8,079.0 8,232.0 8,834.0 8,304.0 8,891.0 9,140.0
Income Tax Expense 2,100.0 1,894.0 2,372.0 2,090.0 2,104.0 2,154.0
Earnings from Cont. Ops. 5,979.0 6,338.0 6,462.0 6,214.0 6,787.0 6,986.0
Earnings of Discontinued Ops. - - - - - -
Extraord. Item & Account. Change - - - - - -
Net Income to Company 5,979.0 6,338.0 6,462.0 6,214.0 6,787.0 6,986.0
Minority Int. in Earnings (33.0) (18.0) (19.0) (36.0) (47.0) (42.0)
Net Income 5,946.0 6,320.0 6,443.0 6,178.0 6,740.0 6,944.0
Pref. Dividends and Other Adj. 6.0 6.0 7.0 7.0 8.0 9.0
NI to Common Incl Extra Items 5,940.0 6,314.0 6,436.0 6,171.0 6,732.0 6,935.0
NI to Common Excl. Extra Items 5,940.0 6,314.0 6,436.0 6,171.0 6,732.0 6,935.0
21
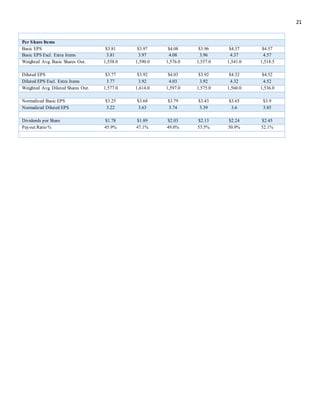
Per Share Items
Basic EPS $3.81 $3.97 $4.08 $3.96 $4.37 $4.57
Basic EPS Excl. Extra Items 3.81 3.97 4.08 3.96 4.37 4.57
Weighted Avg. Basic Shares Out. 1,558.0 1,590.0 1,576.0 1,557.0 1,541.0 1,518.5
Diluted EPS $3.77 $3.92 $4.03 $3.92 $4.32 $4.52
Diluted EPS Excl. Extra Items 3.77 3.92 4.03 3.92 4.32 4.52
Weighted Avg. Diluted Shares Out. 1,577.0 1,614.0 1,597.0 1,575.0 1,560.0 1,536.0
Normalized Basic EPS $3.25 $3.68 $3.79 $3.43 $3.65 $3.9
Normalized Diluted EPS 3.22 3.63 3.74 3.39 3.6 3.85
Dividends per Share $1.78 $1.89 $2.03 $2.13 $2.24 $2.45
Payout Ratio % 45.9% 47.1% 49.0% 53.5% 50.9% 52.1%
22
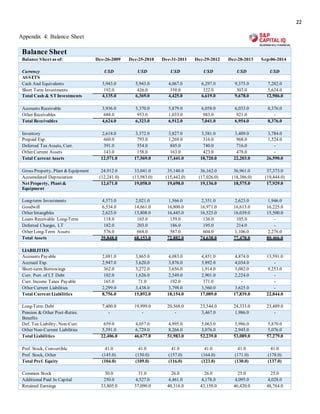
Appendix 4: Balance Sheet
Balance Sheet
Balance Sheet as of: Dec-26-2009 Dec-25-2010 Dec-31-2011 Dec-29-2012 Dec-28-2013 Sep-06-2014
Currency USD USD USD USD USD USD
ASSETS
Cash And Equivalents 3,943.0 5,943.0 4,067.0 6,297.0 9,375.0 7,282.0
Short Term Investments 192.0 426.0 358.0 322.0 303.0 5,624.0
Total Cash & ST Investments 4,135.0 6,369.0 4,425.0 6,619.0 9,678.0 12,906.0
Accounts Receivable 3,936.0 5,370.0 5,879.0 6,058.0 6,033.0 8,376.0
Other Receivables 688.0 953.0 1,033.0 983.0 921.0 -
Total Receivables 4,624.0 6,323.0 6,912.0 7,041.0 6,954.0 8,376.0
Inventory 2,618.0 3,372.0 3,827.0 3,581.0 3,409.0 3,784.0
Prepaid Exp. 660.0 793.0 1,269.0 316.0 968.0 1,524.0
Deferred Tax Assets, Curr. 391.0 554.0 845.0 740.0 716.0 -
Other Current Assets 143.0 158.0 163.0 423.0 478.0 -
Total Current Assets 12,571.0 17,569.0 17,441.0 18,720.0 22,203.0 26,590.0
Gross Property, Plant &Equipment 24,912.0 33,041.0 35,140.0 36,162.0 36,961.0 37,373.0
Accumulated Depreciation (12,241.0) (13,983.0) (15,442.0) (17,026.0) (18,386.0) (19,444.0)
Net Property, Plant &
Equipment
12,671.0 19,058.0 19,698.0 19,136.0 18,575.0 17,929.0
Long-term Investments 4,573.0 2,021.0 1,566.0 2,351.0 2,623.0 1,946.0
Goodwill 6,534.0 14,661.0 16,800.0 16,971.0 16,613.0 16,225.0
Other Intangibles 2,623.0 13,808.0 16,445.0 16,525.0 16,039.0 15,500.0
Loans Receivable Long-Term 118.0 165.0 159.0 136.0 105.0 -
Deferred Charges, LT 182.0 203.0 186.0 195.0 214.0 -
Other Long-Term Assets 576.0 668.0 587.0 604.0 1,106.0 2,276.0
Total Assets 39,848.0 68,153.0 72,882.0 74,638.0 77,478.0 80,466.0
LIABILITIES
Accounts Payable 2,881.0 3,865.0 4,083.0 4,451.0 4,874.0 13,591.0
Accrued Exp. 2,947.0 3,620.0 3,876.0 3,892.0 4,034.0 -
Short-term Borrowings 362.0 3,272.0 3,656.0 1,914.0 3,082.0 9,253.0
Curr. Port. of LT Debt 102.0 1,626.0 2,549.0 2,901.0 2,224.0 -
Curr. Income Taxes Payable 165.0 71.0 192.0 371.0 - -
Other Current Liabilities 2,299.0 3,438.0 3,798.0 3,560.0 3,625.0 -
Total Current Liabilities 8,756.0 15,892.0 18,154.0 17,089.0 17,839.0 22,844.0
Long-Term Debt 7,400.0 19,999.0 20,568.0 23,544.0 24,333.0 23,489.0
Pension & Other Post-Retire.
Benefits
- - - 3,467.0 1,986.0 -
Def. Tax Liability, Non-Curr. 659.0 4,057.0 4,995.0 5,063.0 5,986.0 5,870.0
Other Non-Current Liabilities 5,591.0 6,729.0 8,266.0 3,076.0 2,945.0 5,076.0
Total Liabilities 22,406.0 46,677.0 51,983.0 52,239.0 53,089.0 57,279.0
Pref. Stock, Convertible 41.0 41.0 41.0 41.0 41.0 41.0
Pref. Stock, Other (145.0) (150.0) (157.0) (164.0) (171.0) (178.0)
Total Pref. Equity (104.0) (109.0) (116.0) (123.0) (130.0) (137.0)
Common Stock 30.0 31.0 26.0 26.0 25.0 25.0
Additional Paid In Capital 250.0 4,527.0 4,461.0 4,178.0 4,095.0 4,028.0
Retained Earnings 33,805.0 37,090.0 40,316.0 43,158.0 46,420.0 48,764.0
23
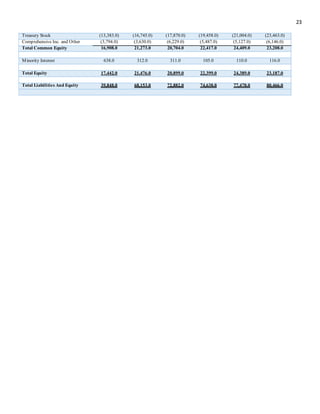
Treasury Stock (13,383.0) (16,745.0) (17,870.0) (19,458.0) (21,004.0) (23,463.0)
Comprehensive Inc. and Other (3,794.0) (3,630.0) (6,229.0) (5,487.0) (5,127.0) (6,146.0)
Total Common Equity 16,908.0 21,273.0 20,704.0 22,417.0 24,409.0 23,208.0
Minority Interest 638.0 312.0 311.0 105.0 110.0 116.0
Total Equity 17,442.0 21,476.0 20,899.0 22,399.0 24,389.0 23,187.0
Total Liabilities And Equity 39,848.0 68,153.0 72,882.0 74,638.0 77,478.0 80,466.0
24
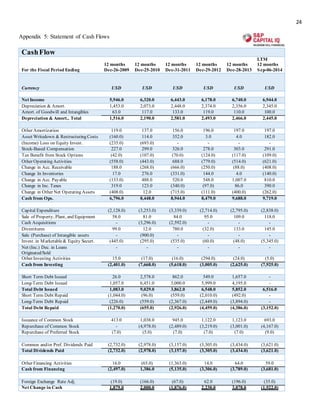
Appendix 5: Statement of Cash Flows
CashFlow
For the Fiscal Period Ending
12 months
Dec-26-2009
12 months
Dec-25-2010
12 months
Dec-31-2011
12 months
Dec-29-2012
12 months
Dec-28-2013
LTM
12 months
Sep-06-2014
Currency USD USD USD USD USD USD
Net Income 5,946.0 6,320.0 6,443.0 6,178.0 6,740.0 6,944.0
Depreciation & Amort. 1,453.0 2,073.0 2,448.0 2,374.0 2,356.0 2,345.0
Amort. of Goodwill and Intangibles 63.0 117.0 133.0 119.0 110.0 100.0
Depreciation & Amort., Total 1,516.0 2,190.0 2,581.0 2,493.0 2,466.0 2,445.0
Other Amortization 119.0 137.0 156.0 196.0 197.0 197.0
Asset Writedown & Restructuring Costs (160.0) 114.0 352.0 3.0 4.0 182.0
(Income) Loss on Equity Invest. (235.0) (693.0) - - - -
Stock-Based Compensation 227.0 299.0 326.0 278.0 303.0 291.0
Tax Benefit from Stock Options (42.0) (107.0) (70.0) (124.0) (117.0) (109.0)
Other Operating Activities (558.0) (443.0) 688.0 (779.0) (514.0) (621.0)
Change in Acc. Receivable 188.0 (268.0) (666.0) (250.0) (88.0) (408.0)
Change In Inventories 17.0 276.0 (331.0) 144.0 4.0 (140.0)
Change in Acc. Payable (133.0) 488.0 520.0 548.0 1,007.0 810.0
Change in Inc. Taxes 319.0 123.0 (340.0) (97.0) 86.0 390.0
Change in Other Net Operating Assets (408.0) 12.0 (715.0) (111.0) (400.0) (262.0)
Cash from Ops. 6,796.0 8,448.0 8,944.0 8,479.0 9,688.0 9,719.0
Capital Expenditure (2,128.0) (3,253.0) (3,339.0) (2,714.0) (2,795.0) (2,838.0)
Sale of Property, Plant, and Equipment 58.0 81.0 84.0 95.0 109.0 118.0
Cash Acquisitions - (3,296.0) (2,592.0) - - -
Divestitures 99.0 12.0 780.0 (32.0) 133.0 145.0
Sale (Purchase) of Intangible assets - (900.0) - - - -
Invest. in Marketable& Equity Securt. (445.0) (295.0) (535.0) (60.0) (48.0) (5,345.0)
Net (Inc.) Dec. in Loans
Originated/Sold
- - - - - -
Other Investing Activities 15.0 (17.0) (16.0) (294.0) (24.0) (5.0)
Cash from Investing (2,401.0) (7,668.0) (5,618.0) (3,005.0) (2,625.0) (7,925.0)
Short Term Debt Issued 26.0 2,578.0 862.0 549.0 1,657.0 -
Long-Term Debt Issued 1,057.0 6,451.0 3,000.0 5,999.0 4,195.0 -
Total Debt Issued 1,083.0 9,029.0 3,862.0 6,548.0 5,852.0 6,516.0
Short Term Debt Repaid (1,044.0) (96.0) (559.0) (2,010.0) (492.0) -
Long-Term Debt Repaid (226.0) (559.0) (2,367.0) (2,449.0) (3,894.0) -
Total Debt Repaid (1,270.0) (655.0) (2,926.0) (4,459.0) (4,386.0) (3,152.0)
Issuance of Common Stock 413.0 1,038.0 945.0 1,122.0 1,123.0 693.0
Repurchase of Common Stock - (4,978.0) (2,489.0) (3,219.0) (3,001.0) (4,167.0)
Repurchase of Preferred Stock (7.0) (5.0) (7.0) (7.0) (7.0) (9.0)
Common and/or Pref. Dividends Paid (2,732.0) (2,978.0) (3,157.0) (3,305.0) (3,434.0) (3,621.0)
Total Dividends Paid (2,732.0) (2,978.0) (3,157.0) (3,305.0) (3,434.0) (3,621.0)
Other Financing Activities 16.0 (65.0) (1,363.0) 14.0 64.0 59.0
Cash from Financing (2,497.0) 1,386.0 (5,135.0) (3,306.0) (3,789.0) (3,681.0)
Foreign Exchange Rate Adj. (19.0) (166.0) (67.0) 62.0 (196.0) (35.0)
Net Change in Cash 1,879.0 2,000.0 (1,876.0) 2,230.0 3,078.0 (1,922.0)
25
Appendix 6: Common Size Income Statement
Income Statement
For the Fiscal Period Ending
Reclassified
12 months
Dec-26-2009
12 months
Dec-25-2010
12 months
Dec-31-2011
12 months
Dec-29-2012
12 months
Dec-28-2013
LTM
12 months
Sep-06-2014
Currency USD USD USD USD USD USD
Revenue 100.0% 100.0% 100.0% 100.0% 100.0% 100.0%
Other Revenue - - - - - -
Total Revenue 100.0% 100.0% 100.0% 100.0% 100.0% 100.0%
Cost Of Goods Sold 46.5% 45.3% 47.4% 47.8% 47.0% 46.5%
Gross Profit 53.5% 54.7% 52.6% 52.2% 53.0% 53.5%
Selling General & Admin Exp. 34.6% 38.1% 36.8% 37.7% 37.9% 37.9%
R & D Exp. - - - - - -
Depreciation & Amort. - - - - - -
Amort. of Goodwill and
Intangibles
0.1% 0.2% 0.2% 0.2% 0.2% 0.1%
Other Operating Expense/(Income) - - - - - -
Other Operating Exp., Total 34.7% 38.3% 37.0% 37.9% 38.1% 38.0%
Operating Income 18.8% 16.4% 15.6% 14.4% 14.9% 15.5%
Interest Expense (0.9%) (1.6%) (1.3%) (1.4%) (1.4%) (1.3%)
Interest and Invest.Income 0.2% 0.1% 0.1% 0.1% 0.1% 0.1%
Net Interest Exp. (0.8% ) (1.4% ) (1.2% ) (1.2% ) (1.2% ) (1.2% )
Income/(Loss) from Affiliates 0.8% 1.3% - - - -
Other Non-Operating Inc. (Exp.) - - - - - -
EBT Excl. Unusual Items 18.9% 16.3% 14.4% 13.1% 13.6% 14.3%
Restructuring Charges (0.1%) - (0.6%) (0.4%) (0.2%) (0.6%)
Merger & Related Restruct.
Charges
(0.1%) (2.0%) (0.5%) (0.0%) (0.0%) (0.0%)
Impairment of Goodwill - - - - - -
Other Unusual Items - - - - - -
EBT Incl. Unusual Items 18.7% 14.2% 13.3% 12.7% 13.4% 13.7%
Income Tax Expense 4.9% 3.3% 3.6% 3.2% 3.2% 3.2%
Earnings from Cont. Ops. 13.8% 11.0% 9.7% 9.5% 10.2% 10.4%
Earnings of Discontinued Ops. - - - - - -
Extraord. Item & Account.Change - - - - - -
Net Income to Company 13.8% 11.0% 9.7% 9.5% 10.2% 10.4%
Minority Int. in Earnings (0.1%) (0.0%) (0.0%) (0.1%) (0.1%) (0.1%)
Net Income 13.8% 10.9% 9.7% 9.4% 10.1% 10.4%
Pref. Dividends and Other Adj. 0.0% 0.0% 0.0% 0.0% 0.0% 0.0%
NI to Common Incl Extra Items 13.7% 10.9% 9.7% 9.4% 10.1% 10.4%
NI to Common Excl. Extra
Items
13.7% 10.9% 9.7% 9.4% 10.1% 10.4%
26
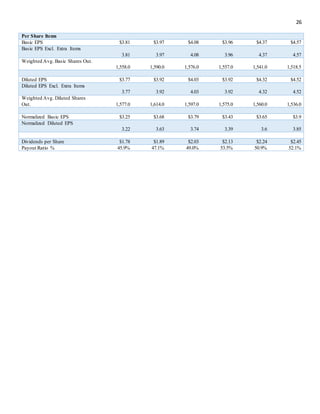
Per Share Items
Basic EPS $3.81 $3.97 $4.08 $3.96 $4.37 $4.57
Basic EPS Excl. Extra Items
3.81 3.97 4.08 3.96 4.37 4.57
Weighted Avg. Basic Shares Out.
1,558.0 1,590.0 1,576.0 1,557.0 1,541.0 1,518.5
Diluted EPS $3.77 $3.92 $4.03 $3.92 $4.32 $4.52
Diluted EPS Excl. Extra Items
3.77 3.92 4.03 3.92 4.32 4.52
Weighted Avg. Diluted Shares
Out. 1,577.0 1,614.0 1,597.0 1,575.0 1,560.0 1,536.0
Normalized Basic EPS $3.25 $3.68 $3.79 $3.43 $3.65 $3.9
Normalized Diluted EPS
3.22 3.63 3.74 3.39 3.6 3.85
Dividends per Share $1.78 $1.89 $2.03 $2.13 $2.24 $2.45
Payout Ratio % 45.9% 47.1% 49.0% 53.5% 50.9% 52.1%
27
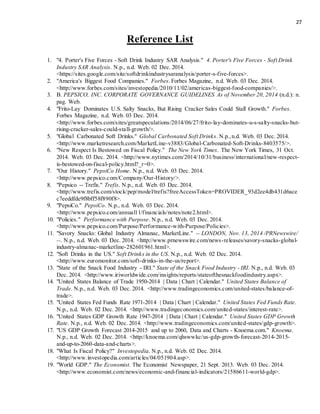
Reference List
1. "4. Porter's Five Forces - Soft Drink Industry SAR Analysis." 4. Porter's Five Forces - Soft Drink
Industry SAR Analysis. N.p., n.d. Web. 02 Dec. 2014.
<https://sites.google.com/site/softdrinkindustrysaranalysis/porter-s-five-forces>.
2. "America's Biggest Food Companies." Forbes. Forbes Magazine, n.d. Web. 03 Dec. 2014.
<http://www.forbes.com/sites/investopedia/2010/11/02/americas-biggest-food-companies/>.
3. B. PEPSICO, INC. CORPORATE GOVERNANCE GUIDELINES As of November 20, 2014 (n.d.): n.
pag. Web.
4. "Frito-Lay Dominates U.S. Salty Snacks, But Rising Cracker Sales Could Stall Growth." Forbes.
Forbes Magazine, n.d. Web. 03 Dec. 2014.
<http://www.forbes.com/sites/greatspeculations/2014/06/27/frito-lay-dominates-u-s-salty-snacks-but-
rising-cracker-sales-could-stall-growth/>.
5. "Global Carbonated Soft Drinks." Global Carbonated Soft Drinks. N.p.,n.d. Web. 03 Dec. 2014.
<http://www.marketresearch.com/MarketLine-v3883/Global-Carbonated-Soft-Drinks-8403575/>.
6. "New Respect Is Bestowed on Fiscal Policy." The New York Times. The New York Times, 31 Oct.
2014. Web. 03 Dec. 2014. <http://www.nytimes.com/2014/10/31/business/international/new-respect-
is-bestowed-on-fiscal-policy.html?_r=0>.
7. "Our History." PepsiCo Home. N.p., n.d. Web. 03 Dec. 2014.
<http://www.pepsico.com/Company/Our-History/>.
8. "Pepsico -- Trefis." Trefis. N.p., n.d. Web. 03 Dec. 2014.
<http://www.trefis.com/stock/pep/model/trefis?freeAccessToken=PROVIDER_93d2ee4db431d6ace
c7eeddfde9f8bff58f890f8>.
9. "PepsiCo." PepsiCo. N.p., n.d. Web. 03 Dec. 2014.
<http://www.pepsico.com/annual11/financials/notes/note2.html>.
10. "Policies." Performance with Purpose. N.p., n.d. Web. 03 Dec. 2014.
<http://www.pepsico.com/Purpose/Performance-with-Purpose/Policies>.
11. "Savory Snacks: Global Industry Almanac, MarketLine." -- LONDON, Nov. 13, 2014 /PRNewswire/
--. N.p., n.d. Web. 03 Dec. 2014. <http://www.prnewswire.com/news-releases/savory-snacks-global-
industry-almanac-marketline-282601961.html>.
12. "Soft Drinks in the US." Soft Drinks in the US. N.p., n.d. Web. 02 Dec. 2014.
<http://www.euromonitor.com/soft-drinks-in-the-us/report>.
13. "State of the Snack Food Industry - IRI." State of the Snack Food Industry - IRI. N.p., n.d. Web. 03
Dec. 2014. <http://www.iriworldwide.com/insights/reports/stateofthesnackfoodindustry.aspx>.
14. "United States Balance of Trade 1950-2014 | Data | Chart | Calendar." United States Balance of
Trade. N.p., n.d. Web. 03 Dec. 2014. <http://www.tradingeconomics.com/united-states/balance-of-
trade>.
15. "United States Fed Funds Rate 1971-2014 | Data | Chart | Calendar." United States Fed Funds Rate.
N.p., n.d. Web. 02 Dec. 2014. <http://www.tradingeconomics.com/united-states/interest-rate>.
16. "United States GDP Growth Rate 1947-2014 | Data | Chart | Calendar." United States GDP Growth
Rate. N.p., n.d. Web. 02 Dec. 2014. <http://www.tradingeconomics.com/united-states/gdp-growth>.
17. "US GDP Growth Forecast 2014-2015 and up to 2060, Data and Charts - Knoema.com." Knoema.
N.p., n.d. Web. 02 Dec. 2014. <http://knoema.com/qhswwkc/us-gdp-growth-forecast-2014-2015-
and-up-to-2060-data-and-charts>.
18. "What Is Fiscal Policy?" Investopedia. N.p., n.d. Web. 02 Dec. 2014.
<http://www.investopedia.com/articles/04/051904.asp>.
19. "World GDP." The Economist. The Economist Newspaper, 21 Sept. 2013. Web. 03 Dec. 2014.
<http://www.economist.com/news/economic-and-financial-indicators/21586611-world-gdp>.